Solar loan vs. lease vs. PPA: Who actually gets the tax credit
It can be tough to choose between loans, leases, and power-purchase agreements. Here’s some information to get you started.
One of the big things we hear from homeowners who want to go solar is that it’s too complicated. That’s especially true when it comes to financing. There are loans, leases, power-purchase agreements (PPAs), all containing different terms, potentially different rates, and qualifying for different incentives. It’s enough to make your head spin.
See estimates with each type of financing with just your ZIP code.
In this article, we’ll try to ease some of that confusion when it comes to financing. We’ll provide the basics on each of the major ways to finance a system, show you where to get more info, and even where to get estimates that show the different options. Let’s get to it.
In this article:
- Three ways to finance solar
- Who actually owns the system, and why it matters
- Who actually gets the tax credit
- Why salespeople blur the line
- How to ask the right questions before you sign
- Frequently asked questions
Three ways to finance solar
Let’s take a quick look at some of the important facts about each financing method.
Quick-reference table:
| Solar Loan | Solar Lease | Solar PPA | |
| Who owns the system | You | Solar company/financier | Solar company/financier |
| Upfront cost | Depends on loan terms | $0 down | $0 down |
| Monthly payment | Loan payment | Fixed monthly fee | Per-kWh rate |
| Tax credits/incentives | You | Solar company/financier | Solar company/financier |
| Net metering benefit | You | Solar company | Solar company |
| End of term | You own it outright | Buy, renew, or remove | Buy, renew, or remove |
| Long-term savings potential | Highest |
Key definitions (brief):
- Solar loan: You borrow money to buy the system and own it from day one.
- Solar lease: You pay a flat monthly fee to use panels owned by a third party. (Full explainer → Solar PPA vs Lease)
- Solar PPA (Power Purchase Agreement): You buy the electricity the panels produce at a discounted per-kWh rate — but the panels belong to the company.
- Prepaid lease: A hybrid — you pay a lump sum upfront for a third-party ownership (TPO) arrangement. (Full explainer → prepaid solar lease)
The type of financing you choose helps determine everything else: How much you pay upfront, how much you pay per month, how much you save. There’s no right answer, it depends on your financial needs, and what you want from your system.
Who actually owns the system — and why it matters
Ownership determines:
- Who gets the federal tax credit
- Who benefits from net metering (selling excess power back to the grid)
- Whether going solar increases your home’s appraised value
- What happens when you sell your house
- Who’s responsible for maintenance and repairs
Loan: You own it.
Lease / PPA / Prepaid lease: The company owns it. Whether it’s the financier, the solar company, or another organization, these are all “third-party ownership” (TPO) models. The panels sit on your roof, but you don’t own them, you just have a contract to use the power or the system.
There’s one thing to note here. If you don’t own the system, it can present potential issues if you want to sell your house. There’s often a way to buy out your lease or PPA before you sell, but it’s important to know the details before signing a contract.
Who actually gets the tax credit
This can get muddy during the sales process, so make sure you ask detailed questions. Here’s the accurate picture as of 2026:
For homeowners who buy with cash or a loan:
- The 30% federal residential clean energy credit (25D) expired at the end of 2025
- New loan/cash purchases in 2026 do not qualify for 25D
- There may still be state incentives you can take advantage of
For TPO (lease, PPA, prepaid lease):
- The solar or financing company claims the 30% commercial clean electricity credit (48E)
- In Energy Communities, the credit can reach 40% (full explainer → energy-communities)
- The credit benefit is theoretically passed through to you in the form of lower monthly payments or a reduced prepaid price, but you never see it as a line item
What “passed through” actually means:
- The solar company prices their lease/PPA products partly based on the tax credit they’ll get
- You benefit indirectly, but you don’t control it, verify it, or receive it directly
- There’s no standard requirement for companies to show you how much of the credit they’re keeping vs. passing on
So, there’s the issue. While the tax credit is presumably used to make your payments lower, there’s no single way to verify it. You kind of take the solar company’s word for it.
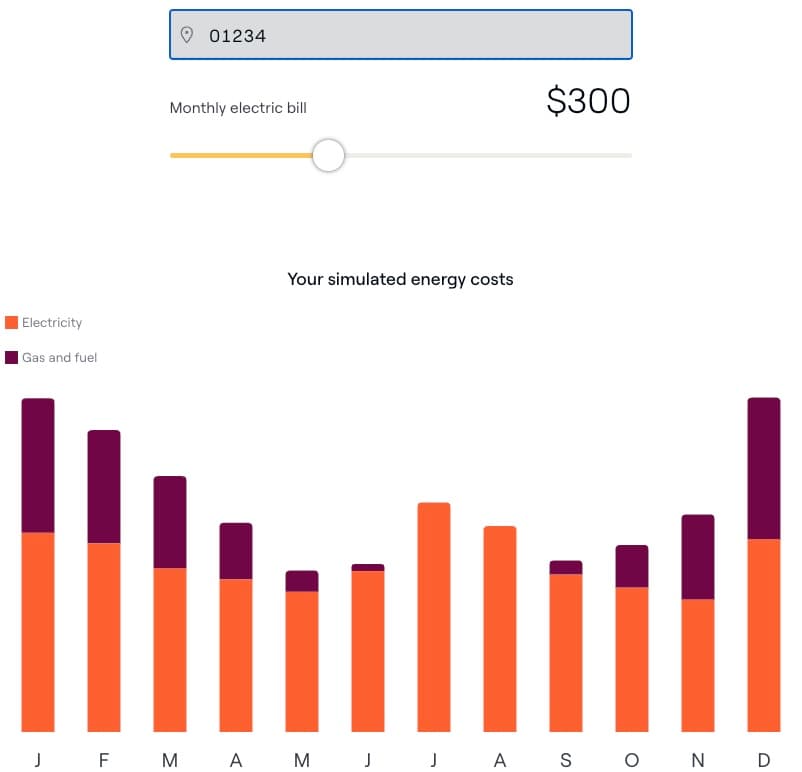
Want to see how much you can save with solar and other electrification projects? Check out our Electrification Calculator.
Why salespeople blur the line
Most solar companies and salespeople do a great job and truly have your best interests in mind. But this “passed through” incentive structure can make it tough for homeowners to get clear answers on what they’re getting. Let’s take a closer look:
The incentive structure:
- TPO products (lease/PPA) are often offered at $0 down, with no credit check complexity, and a simple pitch
- Commissions now sometimes favor selling TPO over loans
- The line of “You still benefit from the tax credit” is technically true but can be misleading if you don’t have full information
With that landscape in mind, there are a few TPO options and framings that are important to be vigilant about, and make sure you get full information:
- “You get the 30% tax credit” on a lease or PPA → Again, you get the company’s 48E credit passed through, not your own
- “This is just like owning it” → It is not. Net metering, home value, and end-of-contract options all differ from a true loan. On the flip side, the owning company is responsible for maintenance, etc.
- Presenting all three options as equivalent → They’re not. The right answer for you depends heavily on your tax situation, how long you’ll stay in the home, and your utility’s net metering policy
Most solar companies and salespeople are truly just doing their best to get a system that meets your needs. As with any industry, though, there are a few bad apples that are trying to get any contract signed and get their commission, nevermind what’s best for you. Make sure you understand exactly what you’re getting, and make sure you go with an installer that explains all the details, answers all your questions, and doesn’t push you in any direction.
How to ask the right questions before you sign
To be sure you’re getting the right deal for you, here are some important questions to ask. Again, a reputable installer will answer these questions clearly, and happily.
“Under this contract, who claims the federal tax credit, me or your company?”
With a loan or cash purchase you get any incentives, remembering that the 25D residential credit is no more. With a lease or PPA the company gets it. How they answer this is important. If they explain the credit carefully, tell you upfront that they get it, and show how they pass the savings along, that’s a great sign.
“How is the tax credit factored into my pricing?”
As we said above, for TPO they should be able to explain how the 48E credit affects your price. If they can’t, that’s a red flag.
“What happens to net metering credits, do they come to me?”
Again, for loan and cash the simple answer is, “Yes!” For TPO the answer is, “No.” Net metering credits typically go to the company that owns the system.
“If I sell my home in 7 years, what happens to this contract?”
Once again, with a loan or cash purchase, you own the system; it transfers with the home as an asset.
With TPO the contract must transfer to the buyer or be bought out, at a cost you should know upfront.
FAQ
Is a solar loan better than a lease?
For most homeowners who plan to stay in their home long-term and have a tax liability to offset, a loan historically offered better total savings. That calculus shifted in 2026 with the expiration of 25D and higher interest rates. Now loans no longer carry the immediate tax credit advantage they once did. The right answer depends on your situation.
Who gets the solar tax credit on a lease or PPA?
The solar company does. They claim the 48E commercial clean electricity credit (30%, or up to 40% in eligible Energy Communities) and factor it into the pricing they offer you. You receive some of the benefit indirectly, but you don’t control or verify how much of it actually reaches you.
Is the federal solar tax credit still available in 2026?
The 30% residential credit (25D) expired at the end of 2025 for homeowners who purchase with cash or a loan. The 48E commercial credit, which applies to TPO (lease/PPA) systems, remains active.
What’s the difference between a solar lease and a PPA?
A lease charges a fixed monthly fee regardless of how much your system produces. A PPA charges a per-kWh rate for the electricity your panels generate. See our full comparison → Solar PPA vs Lease.
Can a salesperson legally tell me I “get” the tax credit on a lease?
This is a gray area. The company does receive a tax credit, and the savings are theoretically passed through to you in pricing. But we think framing it as “you get the tax credit” implies a direct benefit you don’t actually receive. Always ask exactly who files for the credit and how it affects your contract price.
What is a prepaid lease, and how does it fit in?
A prepaid lease is a TPO arrangement where you pay a lump sum upfront instead of monthly. The solar company still owns the system and claims the tax credit. Generally these have a term of six years or so, then ownership transfers to the homeowner, making it an interesting option. For more, see our prepaid lease explainer.